Brazil Tax Reform Forces Urgent ERP Overhaul for 2027 Compliance
New federal and subnational tax mandates require immediate reconfiguration of enterprise resource planning systems to avoid automated invoice rejection.
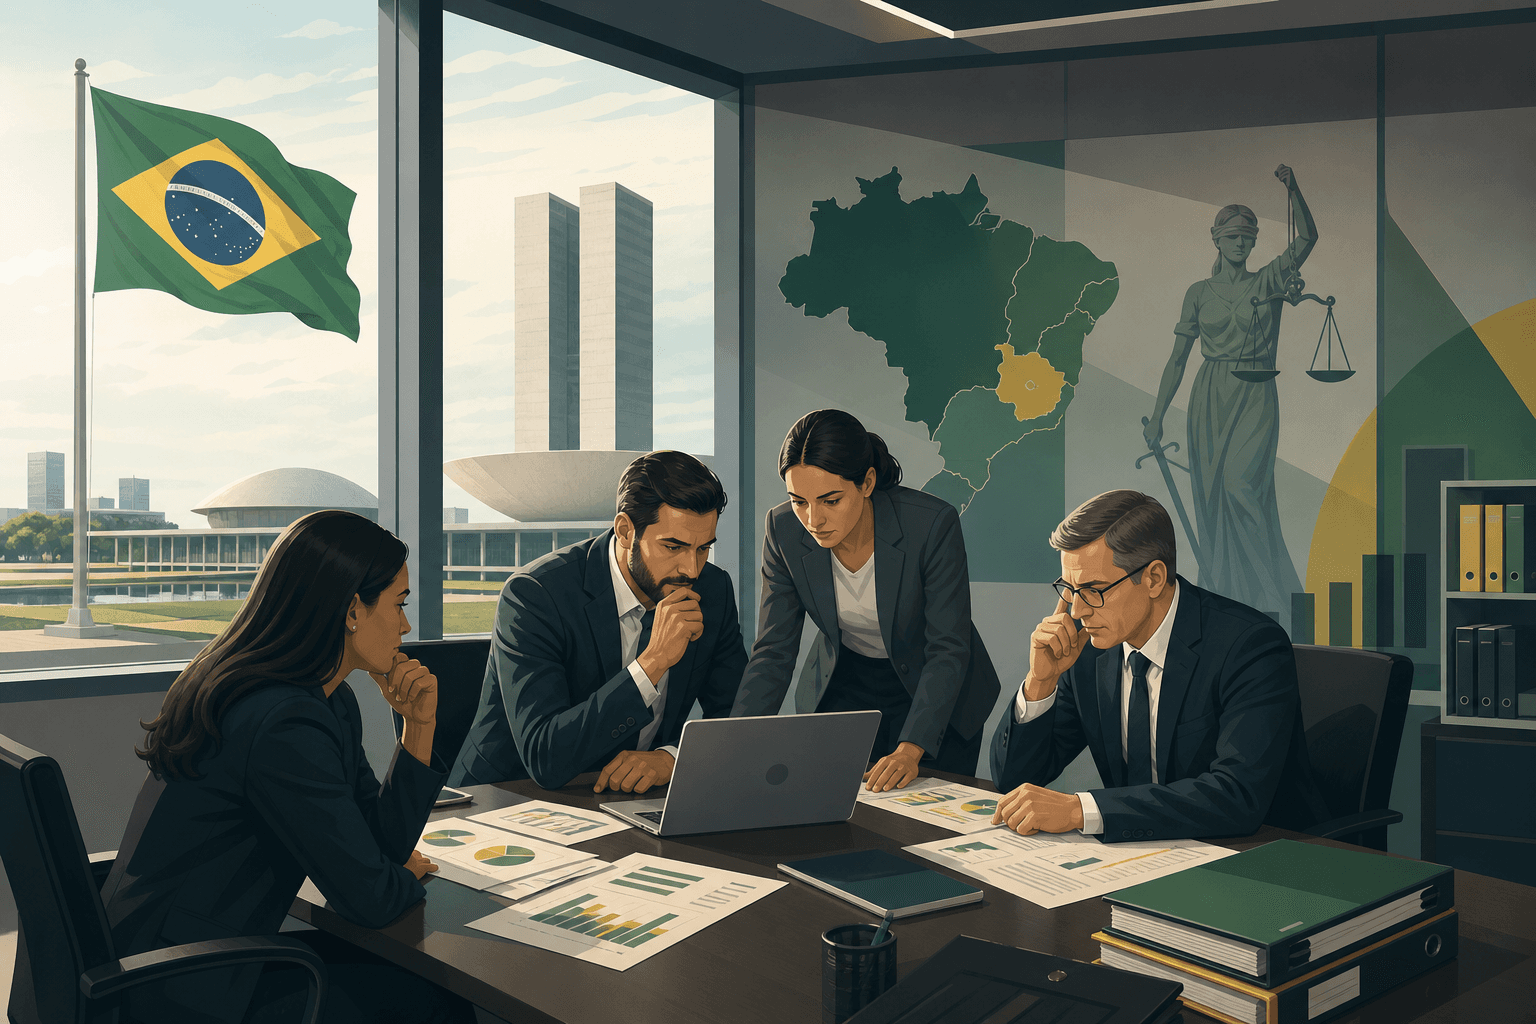
Brazil is mandating a fundamental shift in its consumption tax architecture, requiring companies to reconfigure their enterprise resource planning systems to accommodate new federal and subnational levies before the January 1, 2027, implementation date. Five major technology associations—Brasscom, Abes, Afrac, Fenainfo, and P&D Brasil—have formally signaled that the current five-month development window is insufficient for the necessary technical integration and validation cycles.
The reform replaces existing federal PIS/Cofins levies and subnational ICMS and ISS taxes with a new federal CBS and a shared IBS framework. This transition requires deep modifications to how organizations calculate, report, and remit taxes across 26 states and 5,570 municipalities. The complexity is compounded by the requirement to maintain legacy tax systems alongside the new infrastructure until the full phase-out concludes in 2032.
A critical technical deadline arrives on July 31, 2026, when service invoices must align with the new model to maintain fiscal validity. By August 3, 2026, the federal tax authority will begin automatically rejecting any electronic invoice that lacks the mandatory CBS and IBS data fields. Because Brazil utilizes a fully digital, mandatory invoicing protocol, any rejection effectively halts the transaction and freezes revenue streams for the affected entity.
Testing environments provided by the federal IT firm Serpro have been available only since July 1, 2026, and remain limited by a lack of real-world transaction data. These test credits expire at the end of the year and are non-transferable, creating a high-pressure environment for developers tasked with building compliant interfaces. The absence of a finalized design for the split payment mechanism further complicates the development of banking and payment processing integrations.
The lack of a unified regulatory repository forces software vendors to monitor thousands of individual municipal and state gazettes to ensure compliance. This fragmentation increases the risk of system inconsistencies and potential downtime during the transition. Enterprise architects must now prioritize the development of flexible, modular tax logic that can adapt to evolving state-level requirements without requiring full system re-deployments.
The current implementation schedule creates significant operational risk for multinational firms relying on global ERP providers like SAP and Oracle. Any delay in the delivery of compliant software updates from these vendors will cascade directly into the local operations of their clients. Organizations must evaluate their current dependency on specific ERP modules and prepare for potential manual workarounds if automated updates fail to meet the August deadlines.
The primary challenge for technical leadership lies in the lack of a single source of regulatory truth, which complicates the design of automated tax calculation engines. Without standardized rules for consumer-facing electronic invoices, companies face a high probability of post-launch errors that could trigger significant financial penalties. The reliance on fragmented municipal standards remains the most significant hurdle for achieving a stable, automated tax compliance posture.
The split payment mechanism represents a major shift in financial infrastructure, as it requires tax amounts to be diverted at the moment of settlement. This change necessitates deep integration between payment processors and government accounts, a process that cannot be finalized until the government releases definitive technical specifications. Failure to synchronize these systems could lead to severe liquidity issues for firms operating on thin margins, forcing a total re-evaluation of current treasury management protocols.
Technical teams should monitor the government for any signals regarding an extension of testing timelines or the release of a centralized regulatory repository. In the absence of such flexibility, organizations must activate contingency plans to mitigate the risk of billing interruptions. The coming months will determine whether the current infrastructure can support the transition without requiring a significant increase in manual oversight and operational overhead, potentially impacting long-term capital allocation strategies for foreign investors.
TAGGED
REFERENCED
- shared IBS frameworkedicomgroup.com
- federal IT firm Serprolhlaw.com.br
- split payment mechanismbrinta.com
RELATED INTELLIGENCE
- ERP
Banking Infrastructure Gaps Threaten Corporate Client Retention
Financial institutions face mounting pressure to modernize their digital service stacks as corporate clients increasingly migrate workflows to specialized fintech providers.
- ERP
SAP Embeds Payment Execution to Decentralize Corporate Treasury Workflows
The integration of direct payment execution into cloud ERP environments challenges traditional banking portal dependencies for enterprise financial operations.
- ERP
Sodiaal Standardizes Global ERP Operations on SAP via Accenture Integration
The French dairy cooperative has consolidated its Canadian subsidiary onto a unified SAP platform to streamline international supply chain management.