Stablecoin-Linked Payment Cards Surpass $1 Billion in Monthly Transaction Volume
Retail adoption of stablecoin-funded payment cards is accelerating as users shift from speculative holding to everyday transactional use.
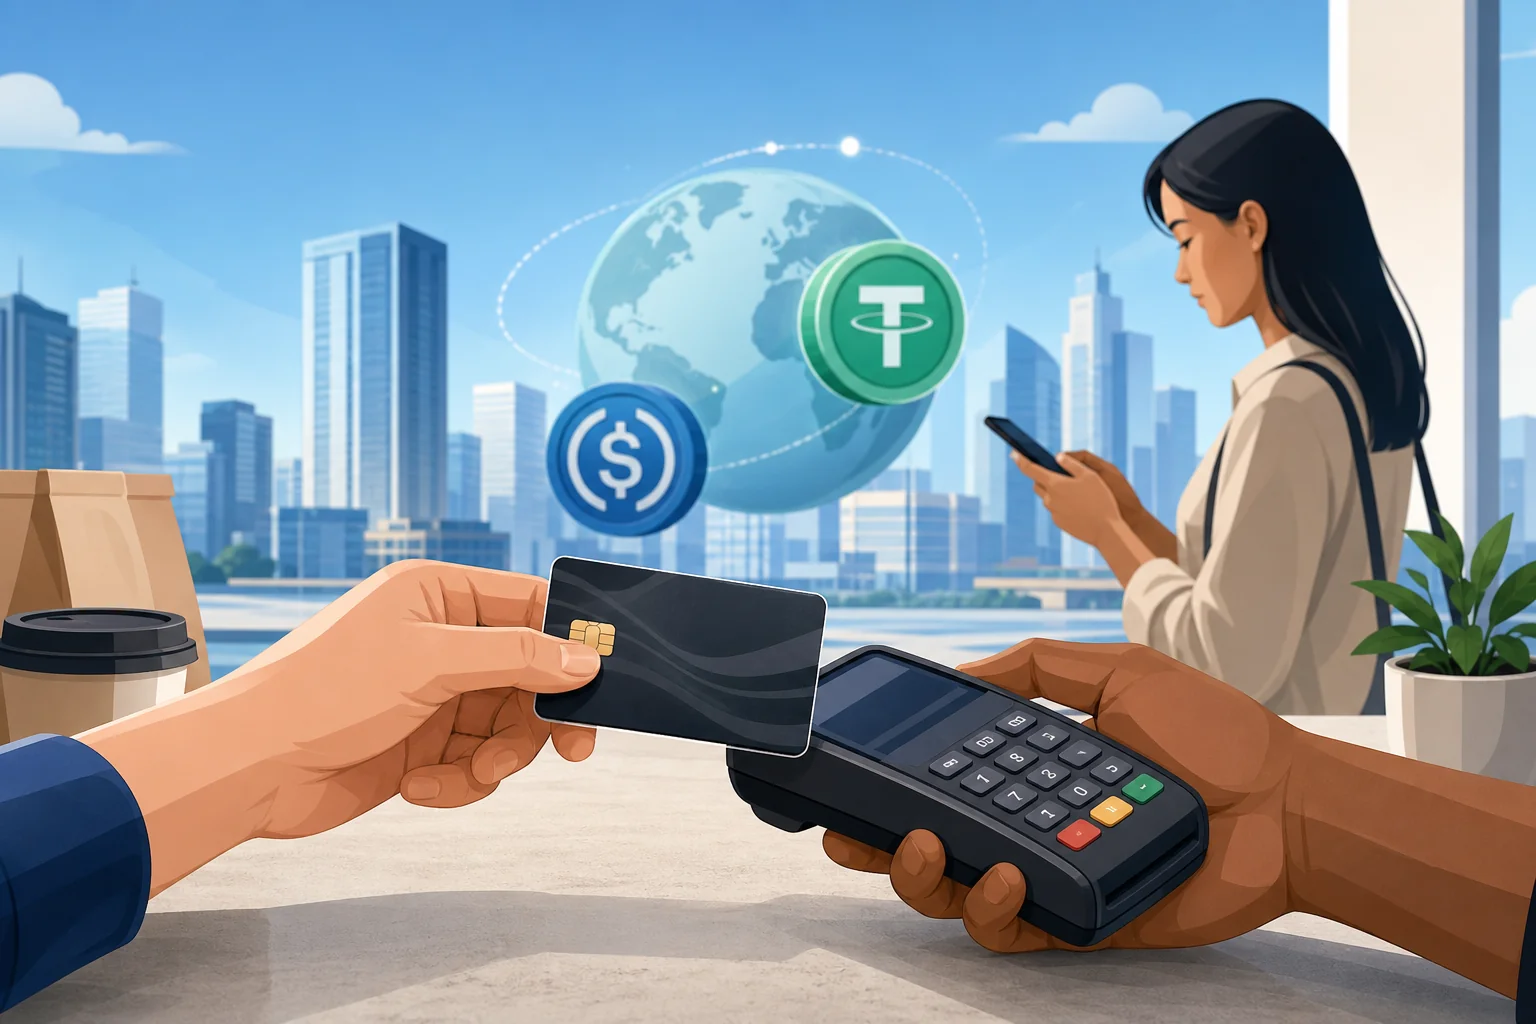
Global transaction volume for crypto-linked payment cards reached $1.04 billion in July 2026, reflecting a tripling of activity compared to the previous year. Data compiled by Paymentscan indicates that dollar-backed stablecoins, specifically USDC and USDT, now facilitate over 70% of these transactions across more than 10 million individual payments.
The average transaction value rose to $86 in July, up from $59 during the same period in 2025, signaling a shift from infrequent, high-value crypto off-ramps to regular, lower-value consumer purchases. This transition is particularly evident in emerging markets, where StraitsX reported a 600% increase in gross transaction volume between early 2025 and 2026. These cards function by converting digital balances into local fiat currency at the point of sale, allowing users to leverage existing payment networks like Visa without requiring merchant-side integration.
Concentration remains a defining characteristic of the current infrastructure, with three platforms—RedotPay, EtherFi, and KAST—accounting for approximately 77% of the tracked volume. RedotPay reported $395.1 million in volume, while EtherFi recorded $100.3 million, excluding fiat-only transfers. The reliance on stablecoins for these transactions reflects users seeking to preserve value against local inflation while maintaining liquidity for daily expenses.
Regional data from Latin America underscores this operational shift, as Oobit reported that grocery stores and food delivery services represent the majority of transaction activity in Brazil and Argentina. Binance data further supports this trend, showing a 53% increase in active card users in Brazil alongside an 80% rise in average transaction volume. Kraken also observed a similar pattern, with weekly payments doubling over the past year as users increasingly utilized assets other than the card’s native currency denomination.
The technical architecture of these cards relies on automated conversion protocols that execute at the moment of authorization to ensure settlement in local fiat currency. These systems must manage the latency between on-chain transaction confirmation and the traditional banking settlement cycles required by card networks. Issuers face significant compliance challenges, as they must perform real-time identity verification and anti-money laundering checks while maintaining the speed required for point-of-sale transactions. The complexity of managing these cross-chain to fiat bridges often dictates the operational overhead for platforms like RedotPay and EtherFi, requiring robust middleware to prevent transaction failures during peak demand periods.
The integration of stablecoins into standard payment rails highlights a functional change in the payment stack, where digital assets act as the primary liquidity layer for retail transactions. While Coinbase retains significant USDC reserves, the company noted that stablecoins are increasingly functioning as the underlying infrastructure for its broader product suite. This development suggests that the technical barrier to entry for consumers is lowering as card issuers standardize the conversion process between digital and fiat assets.
Enterprise leaders should monitor the regulatory and operational implications of this shift, as the reliance on third-party issuers for conversion introduces new counterparty risks. The move toward using stablecoins for everyday transactions necessitates a closer evaluation of how these payment flows interact with existing financial infrastructure and compliance frameworks. As card networks continue to expand support for stablecoin-linked programs, the stability and liquidity of the underlying assets become critical components of the payment stack. Organizations must also consider the implications of jurisdictional fragmentation, where varying legal definitions of stablecoins may impact the interoperability of these cards across different geographic regions.
Future growth will likely depend on the ability of issuers to maintain low-latency conversion processes while scaling to meet demand in diverse economic environments. Monitoring the divergence between stablecoin holdings and actual spending volume will provide insight into whether these assets are becoming primary payment rails or remaining secondary liquidity buffers. Organizations should prepare for increased scrutiny regarding the transparency of self-reported transaction data as these platforms scale to meet global consumer demand.
TAGGED
REFERENCED
- gross transaction volumestraitsx.com
RELATED INTELLIGENCE
- DATA
Globe Telecom quantifies AI ROI through operational integration
Globe Telecom reports P1.2 billion in business benefits from AI initiatives, shifting focus from adoption to measurable financial outcomes.
- DATA
Witchbox Deploys AI-Driven Posture Analytics to Replace Legacy Hardware
Witchbox is transitioning posture assessment from high-cost hardware to mobile-based software, targeting global fitness and rehabilitation markets.
- DATA
Automating Billing Integrity to Close Revenue Leakage Gaps
Regulatory shifts toward real-time transaction monitoring demand that enterprises move from manual audit sampling to automated, continuous billing validation.